

Budget Calendar analysis by Appwee
Managing money becomes much easier when I can see it in the same place as the rest of my week. That is the main appeal of Budget Calendar, a finance app from MiShell Software Systems that puts budgeting into a calendar-style view instead of asking me to think only in categories, charts, or account balances. I found the approach especially useful for planning upcoming bills and checking whether a future week looks comfortable before spending.
The app costs $4.95, is rated for Everyone, and runs on Android 7.0 or later. It has been available since May 17, 2013, and the current version is 1.69. With a 4.8 average from over 480 ratings and more than 10K installs, it has attracted a relatively focused audience rather than trying to be an all-purpose banking platform. That distinction matters: I see it as a planning tool first, not a replacement for a bank app or a complete financial service.
Planning money from a calendar instead of a spreadsheet
The baseline workflow is simple but surprisingly practical
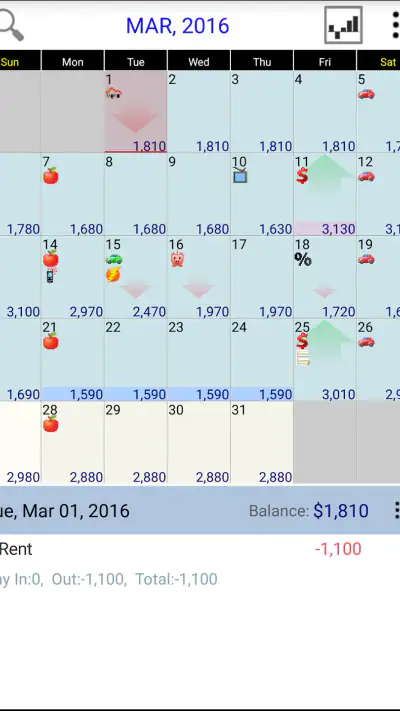
My preferred way to use Budget Calendar is to begin with the events that are hardest to ignore: rent, utilities, subscriptions, loan payments, and regular income. Once those entries are placed on their expected dates, the calendar starts to answer a more useful question than “How much money do I have?” It shows me when money is likely to arrive, when it is committed, and which parts of the month may become tight.
That date-based view is the app’s strongest idea. A category list can tell me that I spend too much on dining, but it does not always show why a particular week feels difficult. A calendar makes timing visible. If several payments land close together, I can see the pressure before the account balance becomes a surprise. For someone paid weekly or irregularly, this can be more helpful than a monthly summary.
I would set up the calendar gradually rather than trying to record every purchase immediately. First, I would enter fixed commitments and dependable income. Then I would add flexible plans, such as groceries, transport, or a planned purchase. This creates a useful baseline without turning the first session into a long data-entry project.
A realistic example is a household that receives income near the start and middle of the month. Rent may be due shortly afterward, while a phone bill and a subscription arrive later. By viewing those events together, I can decide whether a discretionary purchase belongs before or after the next income date. The app does not make that decision for me, but it makes the timing visible enough for me to make it deliberately.
Why the calendar view beats the usual alternatives in some situations
Traditional spreadsheet budgeting gives me flexibility, but it also expects me to design the structure, formulas, and visual summaries myself. A banking app is excellent for checking completed transactions and current balances, yet it may not be the best place to model a future month. Category-based budget apps are often stronger when the main goal is analyzing spending habits across restaurants, transport, shopping, and other labels.
Budget Calendar sits in a narrower space. It is most useful when the question is “What happens around this date?” rather than “What percentage of my income went to this category?” I would choose it over a spreadsheet when I want a quick visual planning surface, and over a bank app when I need to think ahead rather than merely inspect the past.
That focus is also a limitation. If I want automatic transaction imports, detailed account reconciliation, investment tracking, or sophisticated reports, I would look elsewhere. The calendar is valuable because it stays understandable; users who need a full financial dashboard may find it too specialized.
Settings worth checking before building a routine
Before relying on the calendar, I would spend a few minutes reviewing the available settings and display choices. The most important goal is consistency: dates, recurring entries, and the way amounts are shown should match how I actually think about my money. A calendar that looks tidy but uses assumptions I do not understand can create false confidence.
I would also check how the app handles the start of the week and the way future dates are presented. These details sound minor, but they affect how quickly I can scan a pay cycle or identify a cluster of bills. If my work schedule follows a Monday-to-Sunday rhythm, a different week layout may make the same information harder to read.
Another useful habit is separating dependable entries from estimates. A salary payment and a variable electricity bill should not carry the same level of certainty in my planning. I would label or record them in a way that reminds me which amounts are fixed and which should be revisited. That distinction prevents the calendar from looking more precise than the underlying information really is.
I would not enter a predicted amount once and forget it. For variable expenses, I would review the figure after a billing cycle and adjust the next occurrence. This turns the calendar into a learning tool: the plan becomes more realistic over time without requiring a complicated forecasting system.
Repeatable patterns make the app faster to use
The quickest results come from repeatable habits rather than constant tinkering. I would reserve a short weekly check-in to look ahead at the next seven to fourteen days, then do a broader monthly review for larger commitments. During the weekly check, I would focus on timing and cash pressure. During the monthly review, I would correct recurring amounts and remove plans that no longer apply.
For recurring obligations, I would create the pattern once and then verify the next occurrence instead of manually rebuilding the same entry every time. The practical advantage is not just speed. Repetition reduces the chance of forgetting a smaller bill that is easy to overlook when I am working from memory.
A helpful shortcut is to use the calendar as a decision checkpoint. Before ordering something expensive or agreeing to a new subscription, I would look at the surrounding dates rather than only the current balance. If the next two weeks already contain several commitments, I can postpone the purchase or place it after a more comfortable income date.
I also like the idea of maintaining a “known commitments first” rule. I would not begin by trying to predict every coffee or impulse purchase. I would make the unavoidable items visible, then use the remaining space to guide flexible spending. This keeps the tool practical and avoids the common budgeting mistake of creating a beautifully detailed plan that is too tedious to maintain.
For couples or families, the calendar can support a shared conversation even if each person handles money differently. One person may prefer account balances while another thinks in dates. Reviewing upcoming commitments together gives both people a common schedule. I would still confirm the actual account balance elsewhere, but the calendar can make household timing easier to discuss.
Where experienced use meets real limits
The app’s planning strength depends on the quality of what I enter. If an income date changes, a bill is paid early, or a recurring amount rises, the calendar can become misleading until I update it. That is not a flaw unique to this app, but its visual clarity makes stale information particularly easy to trust.
I would therefore avoid treating every future amount as guaranteed. For uncertain income, I would plan conservatively and avoid spending based on money that has not arrived. For variable bills, I would leave some room rather than budgeting down to the last unit. The calendar is best used as a forecast, not as proof that funds are available.
Another trade-off is that a date view can make timing clear while making category analysis less central. If my main problem is overspending on a specific type of purchase, a dedicated expense tracker may teach me more. Budget Calendar can help me reserve money for a category, but I would not expect it to replace detailed spending analysis when that is my primary goal.
I would also think carefully before using it as the only record for important financial decisions. A planning calendar is convenient, but I still want to verify transactions and balances through my financial institution. This two-tool approach works well: the bank app tells me what happened, while Budget Calendar helps me prepare for what is coming.
Who will appreciate it, and who should skip it
I think the app is a strong fit for people who regularly ask whether they can make it through the next pay cycle, freelancers who need to map uneven income, and households with many recurring bills. It is also suitable for anyone who finds spreadsheets intimidating but wants more foresight than a basic account-balance screen provides.
It may be especially useful for a person who has enough income overall but struggles with timing. In that situation, the problem is not necessarily spending too much across the entire month; it may be that several obligations arrive before the next payment. A calendar can expose that pattern immediately and encourage better spacing of purchases.
I would skip it if I want automatic financial aggregation, investment management, advanced reports, or a highly automated expense-capture system. I would also hesitate if I know I will not maintain future entries. No calendar budget can remain useful when its recurring items and estimates are left untouched for months.
The price is another point to consider. At $4.95, it is a paid app rather than a free experiment, so I would want the calendar method to match my habits before committing. For someone who already keeps a paper planner or spreadsheet and enjoys that process, the purchase may not add enough. For someone who repeatedly forgets upcoming bills, the focused format can justify the cost.
My verdict after using its planning style
Budget Calendar succeeds because it makes budgeting feel connected to real life. Bills happen on dates, pay arrives on dates, and financial stress often appears when those dates collide. By putting those events into one view, the app gives me a practical way to plan without forcing me into a complicated financial system.
The best results come from using it with discipline but not obsessively: enter dependable commitments, distinguish estimates from certainties, review the next couple of weeks, and update recurring amounts when reality changes. Those habits turn a basic calendar into a useful early-warning system.
My final recommendation is positive for users who want forward-looking budget planning and prefer a visual schedule over categories or spreadsheets. I would not call it a complete personal-finance replacement, and I would pair it with a bank app for confirmed balances and transactions. Within its narrower purpose, though, Budget Calendar is a focused tool that rewards regular, realistic planning. If your biggest money question is whether upcoming dates will fit together, this is the kind of app I would recommend trying.
Gallery
Budget Calendar Pros and Cons
- Clear calendar view makes upcoming income and expenses easy to understand.
- Flexible recurring transactions help track regular bills and subscriptions.
- Budget categories make it easier to spot spending patterns.
- Useful reminders can reduce the risk of missing payment dates.
- Works well for users who prefer planning finances visually.
- Initial setup can take time when adding accounts
- categories
- and transactions.
- Some advanced budgeting tools may require a paid upgrade.
- Manual entry may feel inconvenient for users expecting automatic bank syncing.
- A busy calendar can become difficult to read with many transactions.
- Limited collaboration features may not suit couples or shared household budgets.
Budget Calendar Frequently Asked Questions
What is Budget Calendar and how does it work?
Budget Calendar is a personal finance app that combines a calendar view with budgeting tools. After entering your income, bills, subscriptions, and other planned expenses, you can see when money is expected to come in and go out. This makes it easier to anticipate low-balance periods, organize recurring payments, and understand your cash flow throughout the month.
Can Budget Calendar help me track recurring bills and subscriptions?
Yes. One of the app’s most useful features is the ability to record recurring financial events, such as rent, utilities, loan payments, streaming services, and salary deposits. You can usually assign dates, amounts, and repetition schedules so future transactions appear automatically. It is still important to review entries regularly because prices, billing dates, and subscription terms can change.
Is Budget Calendar suitable for beginners who have never used a budgeting app?
Budget Calendar is generally approachable for beginners because its calendar-based layout presents financial information in a familiar format. Instead of relying only on lists or complicated reports, you can view upcoming income and expenses by date. New users may need a little time to enter their regular transactions and categories, but the setup becomes more useful as the information grows.
Does Budget Calendar connect directly to my bank account?
Bank connectivity can depend on the specific version, platform, region, and features offered by the developer. Some users may need to enter transactions manually rather than authorize direct account access. Before downloading, check the app’s current store description and privacy information to confirm whether bank synchronization, imported transactions, or other automatic tracking options are supported on your device.
Is my financial information safe when using Budget Calendar?
Before adding sensitive financial details, review the app’s privacy policy, permissions, backup options, and data-storage practices. Avoid entering complete card numbers, passwords, or banking login credentials unless the app clearly explains secure handling and encryption. Using a device passcode, keeping the application updated, and choosing a strong account password can provide additional protection for your budgeting information.














